Storm damage & insurance
Hail or wind damage? We will help you through the entire claim.
Free inspections, documented photo reports and an experienced project manager at your adjuster meeting — then a full restoration by the same team.
Signs of damage
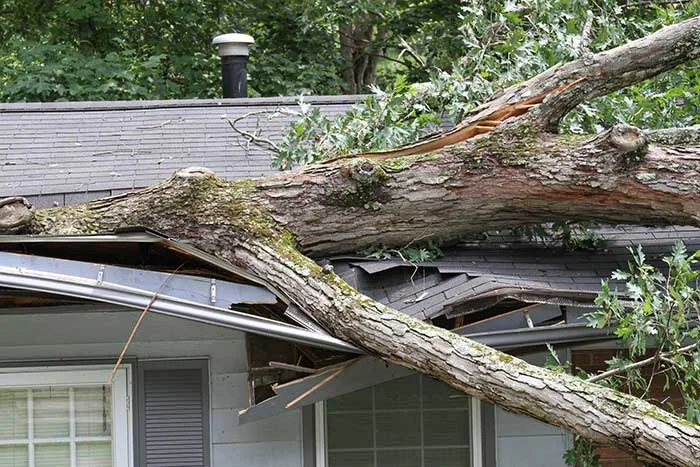
Storm damage isn't always visible from the ground.
Hail bruises shingles and knocks off the granules that protect them from the sun. Wind lifts tabs and breaks the seal strip. Either can lead to leaks months later — and most policies set a deadline to file.
- Dents in gutters, downspouts, vents or the AC unit
- Granules collecting at downspout outlets
- Missing, creased or lifted shingles after high wind
- Cracked or split siding, damaged window screens
- New water stains on ceilings or in the attic
The process
Six steps from storm to finished roof.
You stay in control of your claim. We bring the documentation, the experience with adjusters, and the crew to do the work right.
Free inspection
We check the roof, gutters, downspouts, siding, windows and interior for storm damage.
Photo report
Every finding is photographed and documented so you and your insurer see exactly what we saw.
File & meet the adjuster
If there's enough damage, we explain how to file and meet your adjuster on-site. If a claim is denied, we can help you request a reinspection.
Review your scope
We walk through the approved estimate with you so you understand what's covered and your deductible.
Restore
Materials delivered, landscaping protected, work completed, magnetic nail sweep and final walkthrough.
Close out
We submit completion documents to your insurer for release of any held-back funds, and register your warranty.
Know your policy
RCV vs. ACV — what it means for you.
How your insurer pays depends on your policy type. We'll help you read your paperwork.
Replacement Cost Value (RCV)
Covers the cost to replace damaged materials, minus your deductible. Insurers often pay in two parts: an initial check, then the held-back depreciation once the work is complete.
Actual Cash Value (ACV)
Pays the current depreciated value of the damaged roof, minus your deductible. Older roofs may receive significantly less, so the inspection report matters.
Your deductible
You are responsible for your deductible on any insurance project. We will never offer to waive or cover it — that's insurance fraud in North Carolina and South Carolina.
Common questions
Storm claim FAQ
Should I call my insurance company or a contractor first?
Many homeowners find it helpful to have an inspection first so they know whether there's meaningful damage before opening a claim. Either way, we can explain the next step.
Does the inspection cost anything?
No. Storm damage inspections are free and there's no obligation to use BGC.
What if my claim is denied?
Denials do happen. If our documentation shows damage the adjuster didn't record, we can help you request a reinspection.
Do you handle more than the roof?
Yes. As a licensed general contractor we also restore storm-damaged siding, gutters, windows, paint and interior ceilings and drywall, so you can work with one company.